
Florida Nonprofit Legal Guide
Florida Nonprofit Formation & Governance Guide
A comprehensive, plain-English guide to starting and governing a nonprofit in Florida — from incorporation and bylaws through 501(c)(3) tax-exempt status, board structure, fiduciary duties, charitable solicitation registration, and ongoing annual compliance.
Attorney-led guidance from Thania Diaz Clevenger, Esq. — admitted to The Florida Bar.
On this page▾
What this guide covers
Starting a nonprofit in Florida involves more than filing formation paperwork. The decisions made at the beginning shape how the organization is governed, how it receives tax-exempt status, how its board operates, and how it stays compliant over time. This guide walks through the full formation and governance lifecycle — from incorporation and bylaws through fiduciary duties, 501(c)(3) recognition, charitable solicitation registration, and ongoing annual compliance — so founders and boards understand each step and where legal counsel can help.
Who this is for: New nonprofit founders, boards forming a new organization, and existing nonprofits correcting formation or governance issues in Florida.
Florida incorporation & Articles of Incorporation
Forming a nonprofit in Florida begins with incorporating as a nonprofit corporation through the Florida Division of Corporations. The founding document — the Articles of Incorporation — establishes the legal entity and must include required provisions such as the corporate purpose, the manner of distribution of assets upon dissolution, and the membership structure (if any).
The Articles of Incorporation should be drafted with tax-exempt status in mind, because the IRS reviews them when evaluating a 501(c)(3) application. Language that is fine for an ordinary corporation may not satisfy the requirements for tax exemption, including the dissolution clause and the exclusive-purpose provisions. For hands-on help, nonprofit formation counsel can ensure the documents align with both state and federal expectations.
EIN requirements
After incorporation, the organization obtains an Employer Identification Number (EIN) from the IRS. The EIN is the organization's federal tax identification number and is required to open a bank account, hire employees, file returns, and apply for tax-exempt status. The EIN application is filed with the IRS and should reflect the organization's exact legal name as shown on its formation documents.
Bylaws
Bylaws are the internal rules that govern how the nonprofit operates — board size and composition, how directors are elected and removed, meeting procedures, officer roles, committees, and amendment procedures. Florida law expects a corporation to adopt bylaws, and the IRS reviews them as part of the tax-exemption application.
Generic bylaws pulled from a template often do not match how an organization actually intends to operate, which can create governance disputes later. Well-drafted bylaws reflect the organization's real structure and decision-making practices. Learn more about nonprofit governance and policy counsel.
Conflict-of-interest policies
A conflict-of-interest policy establishes how the organization identifies, discloses, and manages situations where a board member's or officer's personal interests could conflict with the organization's interests. The IRS expects 501(c)(3) organizations to adopt a conflict-of-interest policy and considers it part of a responsible governance framework. Other commonly recommended policies include a document retention policy and a whistleblower policy.
Initial organizational meeting
After incorporation, the new corporation holds its initial organizational meeting, where the board adopts bylaws, elects officers, authorizes the EIN and bank account, and records the first board resolutions. Properly documenting this meeting — and every subsequent board meeting — in meeting minutes is part of maintaining the corporate record the IRS and state regulators may later review.
Board structure & officer roles
A nonprofit's board provides governance and oversight. Most states require a minimum of three directors; best practice is often an odd number (typically five to nine) to avoid tie votes. The bylaws define officer roles, which commonly include:
President / Board Chair
Provides board leadership, sets meeting agendas, and ensures the board carries out its governance responsibilities.
Vice President
Supports the chair and steps in when the chair is unavailable; may lead committees or special projects.
Secretary
Maintains corporate records, meeting minutes, and official documents; supports governance documentation.
Treasurer
Oversees financial oversight and reporting responsibilities; works with leadership and the board on budget and financial governance.
Clear boundaries between founder, employee, and board roles help prevent governance confusion. See the Board Governance Center for tools and guidance on board structure.
Fiduciary responsibilities
Board members of a nonprofit owe fiduciary duties to the organization. These core duties are widely described as:
Duty of Care
Board members must exercise reasonable care and informed judgment, attending to the organization's affairs with the attention a reasonably prudent person would use.
Duty of Loyalty
Board members must put the organization's interests above personal or other interests, and act to avoid conflicts of interest.
Duty of Obedience
Board members must ensure the organization carries out its mission and complies with applicable laws and its own governing documents.
Understanding these duties is essential before accepting a board seat. The fiduciary duties guide in the Board Governance Center explains them in more detail.
IRS Form 1023 / 1023-EZ & 501(c)(3) requirements
Forming the state entity does not, by itself, make an organization tax-exempt. To be recognized as a 501(c)(3) public charity, the organization applies to the IRS using Form 1023 (the full application) or Form 1023-EZ (a streamlined application for smaller organizations that meet specific eligibility criteria, including projected gross receipts and asset thresholds).
The application asks for details about the organization's purpose, activities, governance structure, finances, and compensation practices. Incomplete or inconsistent answers can delay approval or trigger follow-up questions. The Articles of Incorporation and bylaws must support the exempt purpose and include required provisions such as the dissolution clause.
When Form 1023-EZ applies: Form 1023-EZ is available to eligible smaller organizations that meet the IRS's stated gross-receipts and asset tests and satisfy the other eligibility questions on the form. Organizations that do not meet the criteria must file the full Form 1023.
Charitable solicitation registration
Many states require nonprofits that solicit donations from their residents to register as a charitable organization before fundraising — often called charitable solicitation registration. Requirements, thresholds, and exemptions vary by state. An organization that fundraises across state lines should review obligations in each state where it solicits. In Florida, registration and renewal requirements are administered by the state's charitable solicitation authority. Coordinating this with the rest of formation is part of nonprofit compliance work.
Ongoing annual compliance
After tax-exempt status is approved, the organization must maintain it. Ongoing compliance typically includes filing the IRS Form 990 series (990, 990-EZ, or 990-N depending on size), filing state annual reports, renewing charitable solicitation registrations where required, keeping accurate corporate records and meeting minutes, and adhering to the organization's exempt purpose. Treating formation as the beginning of an ongoing legal framework — rather than a one-time filing — helps protect the organization's status over time. Many organizations handle this through fractional general counsel or ongoing compliance support.
Board governance
Strong governance is the foundation of a resilient nonprofit. As organizations grow, informal practices often need to be replaced with clear policies and documented decision-making. Governance work typically includes reviewing and amending bylaws, clarifying board responsibilities and authority, adopting conflict-of-interest and other policies, and documenting board decisions carefully.
The Mission Impact Board Governance Center brings together governance tools and guides — including a board governance dashboard, fiduciary duties guide, and meeting minutes checklist — to help boards operate with clarity. For attorney-supported governance work, see governance & policies counsel.
Common nonprofit startup mistakes
Avoidable formation mistakes can create governance and compliance problems that are more expensive to fix later. Common pitfalls include:
- Choosing a structure before clarifying the organization's purpose
- Using generic bylaws that do not reflect how the organization will operate
- Failing to define board authority and officer responsibilities
- Mixing founder, employee, and board roles without clear boundaries
- Overlooking conflicts of interest
- Applying for tax-exempt status before the organization is structurally ready
- Failing to plan for state registration and ongoing compliance
- Treating formation as a one-time filing rather than the start of an ongoing legal framework
Timelines
State formation
Typically a few days to a few weeks, depending on state processing and expedited options.
Form 1023-EZ
Often a few weeks when eligible, subject to IRS processing volume.
Full Form 1023
Often several months, depending on complexity and IRS backlog.
Legal costs & flat-fee options
Nonprofit legal costs depend on the scope of work. Formation and tax-exemption applications are often handled on a flat-fee basis so founders can budget predictably, while governance review, contract work, and ongoing counsel may be structured as project work, hourly, or a recurring retainer. Mission Impact offers transparent, predictable pricing for nonprofits.
When to involve legal counsel
It is possible to file formation documents without an attorney, but counsel helps ensure the structure, bylaws, and tax-exemption application are completed correctly and tailored to the organization's goals. Legal counsel is especially useful when:
- New nonprofit founders
- Community-based organizations
- Charitable organizations
- Foundations
- Faith-based organizations
- Advocacy and educational organizations
- Mission-driven initiatives becoming formal entities
- Existing organizations correcting formation or governance issues
Your counsel
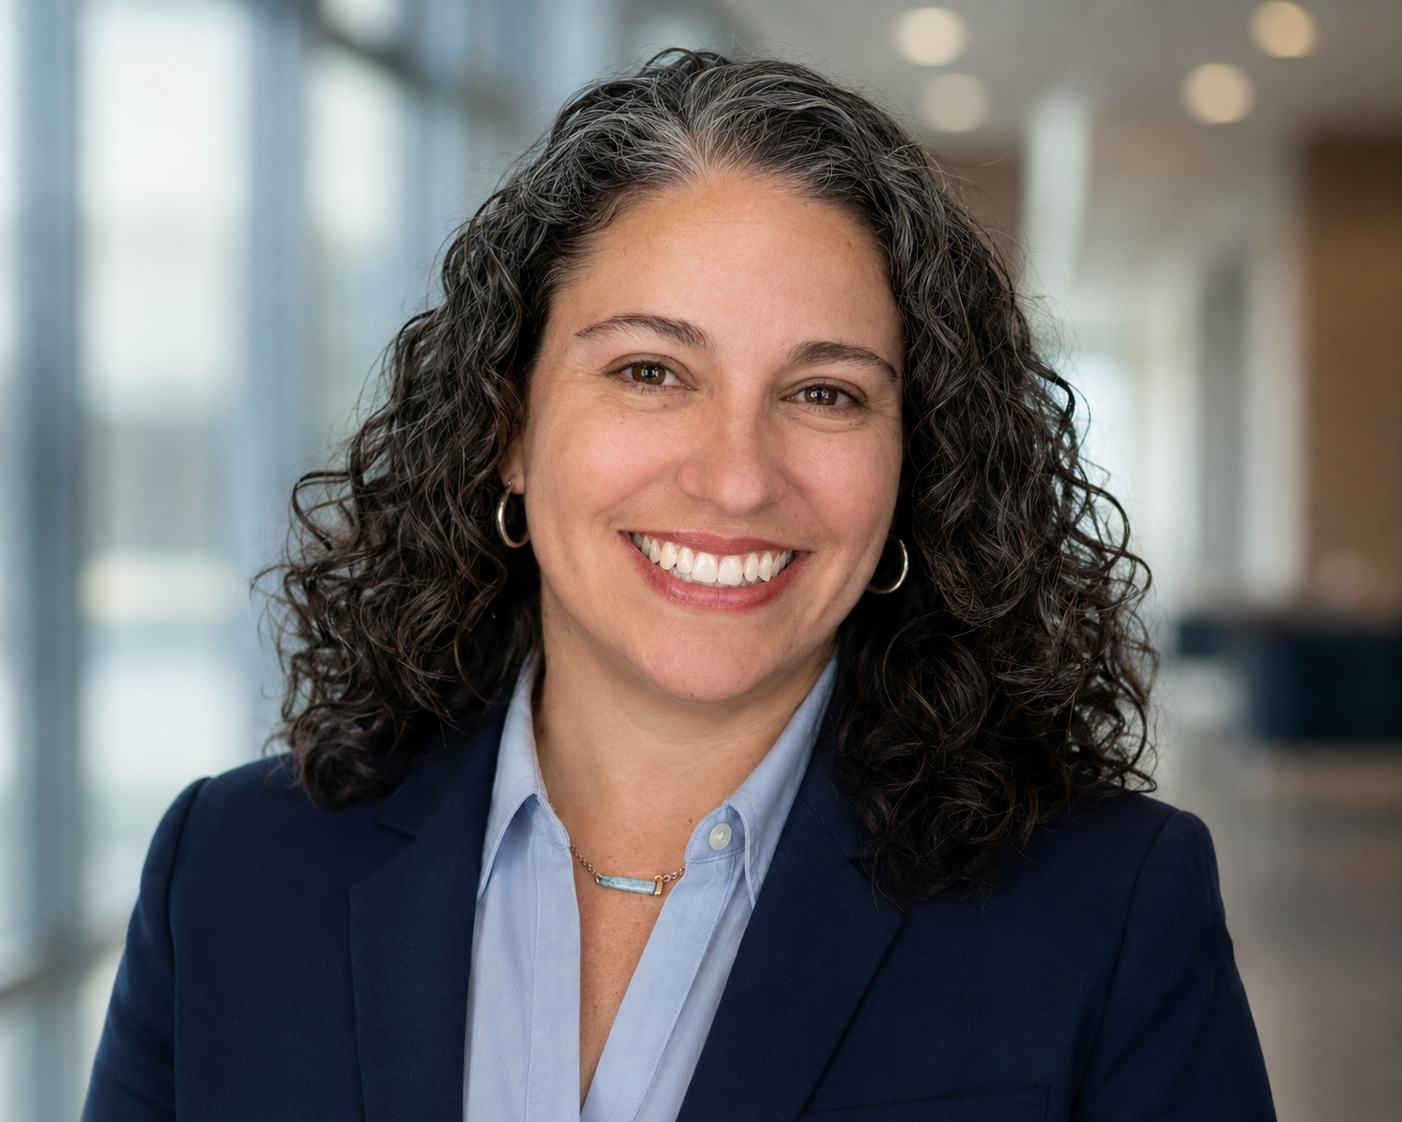
Thania Diaz Clevenger, Esq. — Founder and Managing Attorney, admitted to The Florida Bar. Her practice focuses on nonprofit formation, 501(c)(3) tax-exempt status, board governance, fiduciary duties, nonprofit compliance, employment law and HR policies, and fractional general counsel.
Meet Thania →Frequently asked questions
This guide is provided for general educational purposes and does not constitute legal advice. Requirements vary by jurisdiction and organization.
Related resources & services
Build your nonprofit on a strong legal foundation
Get clarity on formation, governance, and compliance before small decisions become expensive problems.
Get ClarityThis information is provided for general educational purposes and does not constitute legal advice. Viewing this page or contacting Mission Impact Legal Advisors does not create an attorney-client relationship.